Building Wealth That Lasts Across Generations
How thoughtful financial planning can help you enjoy your wealth today while preparing the next generation for tomorrow.
Over the coming decades, a significant amount of wealth is expected to pass from one generation to the next.
Research from Vanguard suggests that more than £7 trillion could be transferred between generations in the UK by 2050.
But passing on wealth is not simply about money changing hands.
Vanguard also highlights research suggesting that 87% of adult children would not retain their parents' financial adviser after receiving an inheritance.
Some may not have an existing relationship with the adviser. Others may use their inheritance to repay a mortgage, support their family or meet other important financial commitments.
And that raises an interesting question.
Is successful intergenerational wealth planning about ensuring the money lasts forever, or ensuring it makes a meaningful difference to the people receiving it?
At Ifamax Wealth Management, we believe the starting point is understanding what you want your wealth to achieve.
For some, that means helping children buy their first home. For others, it may mean supporting grandchildren through education or building a financial legacy that could benefit several generations.
But before considering what you might give away, there is something even more important to understand.
Your Retirement Income Comes First
Retirement can last 30 years or longer.
During that time, your income needs may change considerably.
You may spend more during the early years of retirement, particularly if you want to travel or enjoy activities that were difficult to fit around your working life.
Later in retirement, your spending patterns may change again. There may also be unexpected costs, including additional care or support.
This is why a significant part of our retirement planning work focuses on creating a sustainable retirement income.
We want to understand whether your pensions, investments and other assets can provide the income you need throughout retirement.
Only then can we start to explore how much wealth might be available to pass on.
This is not about discouraging generosity.
It is about helping you understand what you can comfortably afford to give away without putting your own future financial security at unnecessary risk.
Building Wealth Starts With Your Own Financial Journey
During our working lives, we generally focus on building wealth.
We contribute to pensions, save through ISAs, invest for the future and perhaps build up wealth through a successful career or business.
But everyone's journey is different.
Some people accumulate substantial assets and eventually find themselves with more than they are likely to need.
Others face unexpected events that affect their finances.
A change in career, divorce, ill health or supporting a family member can all change the direction of a financial plan.
That is why we start by understanding your values, priorities and goals rather than focusing solely on the amount of money you have.
For some clients, the priority will be preserving wealth to support retirement.
For others, there may be an opportunity to build a meaningful financial legacy.
Neither outcome is right or wrong.
The important thing is understanding what is possible and having a financial plan that can adapt as circumstances change.
When Should You Pass Wealth to the Next Generation?
There is an understandable temptation to help children or grandchildren while you are still alive.
You may want to see them buy their first home, reduce a mortgage or enjoy opportunities that would otherwise be difficult to afford.
And there can be considerable satisfaction in seeing the difference that financial support makes.
But the timing of gifting needs careful thought.
Imagine giving away 20% of your wealth at age 60 and then living for another 35 or 40 years.
Would the remaining assets still provide sufficient income?
What happens if investment returns are lower than expected or your expenditure is higher?
These are questions that can be explored through financial planning and cashflow modelling.
The starting point should always be what you can afford to give away, rather than simply how much you would like to give.
Three Ways to Consider Gifting Wealth
There are several ways to pass wealth to the next generation, each with different tax considerations.
1. Using annual gifting exemptions
The annual Inheritance Tax gifting exemption is currently £3,000 per person, with the ability to carry forward unused exemption from the previous tax year.
Other exemptions may be available, including small gifts and gifts made in connection with weddings or civil partnerships.
2. Making regular gifts from surplus income
Where you have income that exceeds your normal expenditure, it may be possible to make regular gifts that qualify for the normal expenditure out of income Inheritance Tax exemption.
There is no fixed monetary limit, but the gifts must meet the relevant conditions, including being made as part of a normal pattern, funded from income and leaving you sufficient income to maintain your usual standard of living.
Keeping clear records is particularly important.
3. Making larger lifetime gifts
Some outright gifts may fall outside your estate for Inheritance Tax purposes if you survive for seven years after making them.
These are commonly referred to as potentially exempt transfers.
However, the rules can be more complicated, particularly where trusts are involved or you continue to benefit from an asset you have given away.
Gifting can therefore involve both financial planning and specialist tax or legal advice.
Helping Children and Grandchildren Build Wealth Early
One of the most interesting aspects of intergenerational planning is that it does not necessarily need to begin when you are approaching retirement.
It can start much earlier.
For parents and grandparents who have sufficient surplus income, regular contributions towards a child's future could make a significant difference over time.
Two options worth considering are Junior pensions and Junior ISAs.
Example One: Building a Retirement Fund Through a Junior Pension
Under current rules, it is generally possible to contribute £2,880 net each tax year to a pension for a child with no earnings.
Basic-rate pension tax relief increases the contribution to £3,600.
Imagine making these contributions every year for 18 years.
The figures could look like this:
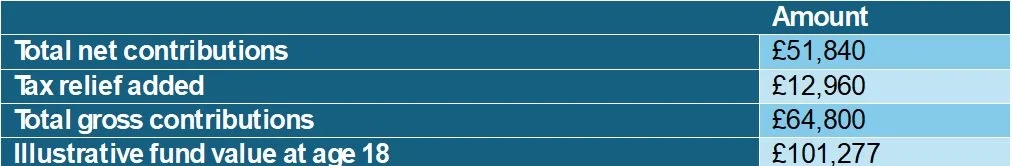
Assuming the money then remains invested, with no further contributions, and continues growing at an illustrative 5% annually, the fund could reach approximately £679,000 by age 57.
That is a substantial amount.
However, inflation will reduce what this money can buy in the future, investment returns are not guaranteed and charges will affect the outcome.
The illustration assumes 5% annual growth after charges, with contributions made at each year-end.
It also illustrates an important principle: by starting early, time can become one of the most valuable elements of an investment strategy.
The trade-off is that pension money is generally inaccessible until the normal minimum pension age, currently scheduled to be 57 from April 2028, subject to exceptions.
For some families, this might be an attractive way to help provide financial security later in life.
Example Two: Helping With a Home or Education Through a Junior ISA
A Junior ISA provides a different type of opportunity.
For the 2026/27 tax year, up to £9,000 can be contributed annually to a child's Junior ISA.
Imagine contributing the maximum amount each year for 16 years.
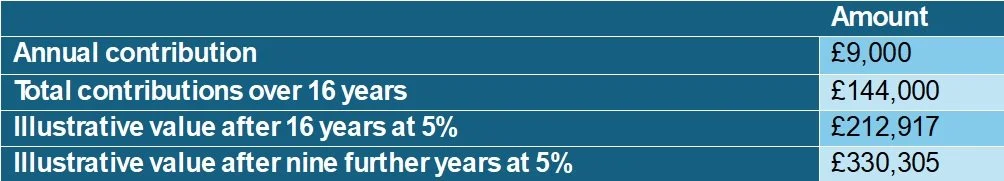
Again, these are illustrations rather than predictions and assume contributions at each year-end, a constant 5% return after charges and no withdrawals.
Unlike a Junior pension, a Junior ISA becomes accessible to the child at age 18.
It automatically converts into an adult ISA, and they can decide whether to retain the investments or withdraw the money.
This is an important distinction.
A Junior ISA could help fund university, a first home or other major life events. But the money legally belongs to the child and they will have control over it as an adult.
The two approaches therefore serve different purposes.
A Junior pension can help build long-term retirement wealth. A Junior ISA provides access much earlier in adult life.
Neither is automatically better.
The right approach depends on the family, the purpose of the money and how much the person making the contributions can afford.
The Other Benefit: Helping the Next Generation Understand Money
There is another reason we believe this type of planning can be valuable.
It creates opportunities for conversations about money.
Building a Junior ISA or pension can be a starting point for helping children understand saving, investing, risk and the importance of long-term decisions.
As children become young adults, these conversations can develop.
They might want to understand how to budget, manage debt, save for a home or make decisions about pensions and investments.
We have always believed that financial planning is about more than money.
It is about helping people understand the choices available to them and giving them confidence in their decisions.
For many families, passing on knowledge and financial confidence can be just as important as passing on the wealth itself.
What Happens if You Have More Wealth Than You Need?
For some families, financial planning may show that their assets are more than sufficient to support their expected lifetime expenditure.
This opens up further opportunities.
It may be appropriate to consider larger lifetime gifts, trusts or other estate planning arrangements.
You may also want to consider whether wealth should pass directly to your children or whether supporting grandchildren would better reflect your family's circumstances.
There are important tax considerations here.
From 6 April 2027, most unused pension funds and pension death benefits will be included within an individual's estate for Inheritance Tax purposes.
For those with substantial pension assets, this makes reviewing beneficiary nominations, retirement income arrangements and wider estate plans particularly important.
However, the changes do not mean pensions should automatically be withdrawn, gifted or passed to a different generation.
The most appropriate approach will depend on the family circumstances, tax position and wider financial plan.
Working alongside solicitors and accountants can be particularly valuable when reviewing these arrangements.
When an Inheritance Doesn't Need to Last Forever
There is one more important point.
We often hear about the importance of preserving wealth across generations.
But is it necessarily a failure if an inheritance is spent?
Imagine someone receives £200,000 and uses it to repay their mortgage.
The inherited money has gone, but the benefit may remain for decades.
Their monthly expenditure could be lower, they may have greater financial security and they might be able to redirect money towards savings, retirement or supporting their own children.
For that family, the inheritance may have achieved exactly what was intended.
The same might apply to funding education, helping with a house deposit or supporting a family member through difficult circumstances.
The value of an inheritance should not be judged solely by how much remains in an investment portfolio.
It should also be considered in terms of the difference it has made to people's lives.
Bringing the Next Generation Into Financial Planning
At Ifamax Wealth Management, we have worked with families across generations for many years.
Sometimes this involves arranging Junior ISAs or pensions.
Sometimes it means helping parents and grandparents explore gifting opportunities.
And sometimes it simply means creating an opportunity for younger family members to start asking questions about money.
We recognise that the next generation may have different goals, different attitudes to investing and different financial needs.
They may also decide to work with a different financial adviser.
That is their choice.
Our focus is on helping our clients and, where appropriate, their families understand their options and make informed decisions.
This can be especially important after a bereavement, when the emotional impact of losing someone may make financial decisions more difficult.
Allowing time, providing clear information and avoiding unnecessary pressure can all be part of a thoughtful approach.
Financial Planning That Supports You and Future Generations
At Ifamax, we have spent more than 20 years helping individuals and families build, protect and preserve their wealth.
As financial planners based in Bristol, we understand that successful wealth management is not simply about growing the value of investments.
It is about understanding what that wealth is for.
For some, the priority is enjoying a comfortable retirement.
For others, it is helping children or grandchildren build a stronger financial future.
And for many, it will be a combination of both.
We typically work with individuals and families who have £400,000 or more in investable assets and want an ongoing financial planning relationship.
If you are an existing client and would like to discuss gifting or involving your family in your financial plans, please contact us. You do not need to wait until your next review.
And if you are considering financial advice and would like to explore how your wealth could support both your retirement and the next generation, we would be pleased to hear from you.
The starting point is not how much wealth you can pass on. It is understanding what you want your wealth to achieve, for you and the people who matter most.
Important note
This article is distributed for educational purposes only and should not be considered investment advice or an offer of any security for sale. This article contains the opinions of the author but not necessarily the Firm and does not represent a recommendation of any particular security, strategy, or investment product. Reference to specific products is made only to help make educational points and does not constitute any form or recommendation or advice. Information contained herein has been obtained from sources believed to be reliable but is not guaranteed. All investment illustrations are hypothetical, assume a constant return of 5% per annum after charges, and are not guaranteed. Actual investment returns will vary, investments can fall in value, and inflation will reduce future purchasing power.
Article Written: November 2026, Tax Rates and Allowances may change in the future.
Useful Links
Case Study: Intergenerational Planning – Retirement Planning & Gifting to Adult Children
Young Adults’ Guide to University